

Ditch: Pay Off Debt Faster
by Ditch Technologies, Inc
4.8
- Safety
- 100% Safe
- Category
- Finance
- Ratings
- 4.8
- Price
- Free
- Download
- 10.00K
This app is secure, reliable, free to install, and offers fast downloads without any risks or malware.
Screenshots
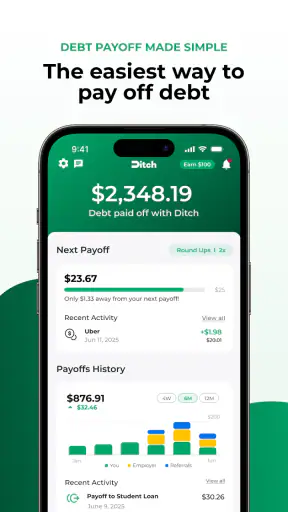
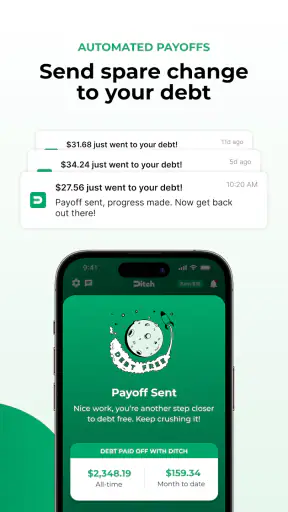
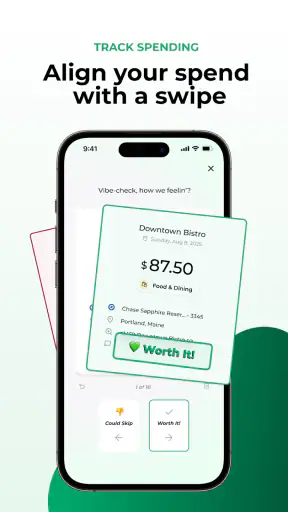
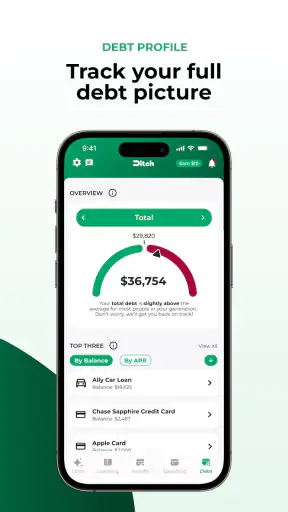
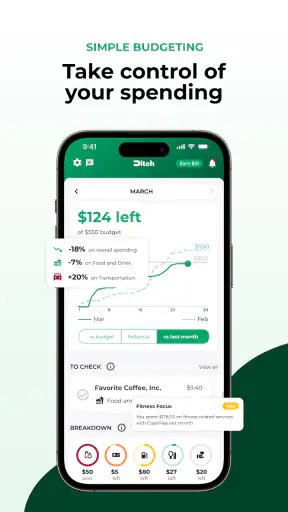
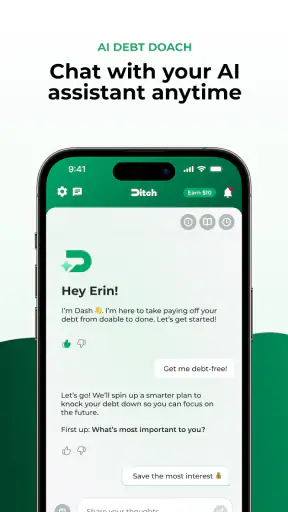
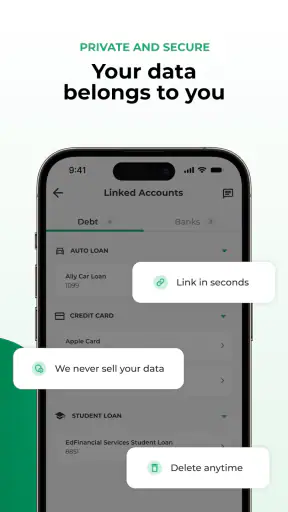
 Analysis by Getfullapps
Debt payoff rarely fails because someone cannot do basic arithmetic. It usually fails because several balances, due dates, interest charges, and competing priorities are spread across different places. Ditch: Pay Off Debt Faster is a finance app from Ditch Technologies, Inc that aims to turn that scattered information into a repeatable payoff routine. After using it as a planning tool, I found its main value is not flashy budgeting; it is the way it encourages you to look at debt as a sequence of manageable decisions.
The app is free to install, with optional in-app purchases ranging from $5.99 to $89.99 per item. It is rated for Everyone, runs on Android 8.0 and later, and its current version is 1.5.6. With a 4.8 average from around 1.1 thousand ratings and more than 10 thousand installs, it has attracted a modest but positive audience. Those figures do not replace personal testing, but they do suggest that the basic idea is resonating with people who want a dedicated debt tool rather than another broad banking dashboard.
Turning a pile of balances into a routine
I find it helpful to treat a debt plan as a routine with a few clear checkpoints, not a promise to make every month perfect. In this section, I’d focus on choosing a review moment you already keep—such as payday—so balance updates and payment choices have a natural place in your week. That simple rhythm also makes it easier to spot when a change calls for a fresh look at the plan.
Start with a complete debt picture
The most useful way to begin is to treat Ditch as a single source of planning information. I would enter every relevant debt carefully instead of starting with only the account that feels most urgent. That means including cards, personal loans, or other balances you are actively trying to reduce, then checking the details before trusting any payoff projection.
This first pass matters because a debt plan is only as useful as its inputs. A missing minimum payment can make a schedule look comfortably affordable when it is not. An incorrect interest rate can change which balance deserves extra attention. I recommend keeping the lender statement open while entering information, then reviewing each field once more before making a payment decision.
Ditch is particularly helpful for people who understand their debts individually but struggle to see the combined picture. A credit-card app may show one balance clearly, while a bank app shows another, and a spreadsheet may contain an older estimate. Bringing the obligations into one payoff-focused workspace reduces the mental switching that makes debt feel larger and less controllable.
Choose a strategy you can actually repeat
Debt payoff methods are often discussed as if one answer works for everyone. In practice, the best method is the one that fits both the numbers and your behavior. A plan that saves interest but becomes too complicated to follow can be weaker in real life than a simpler plan you maintain every month.
Articles to Explore Next

Uber Eats Makes Dinner Easier to Manage, but the Fees Add Up

Google Photos Turns a Camera Roll Into a Library You Can Find Your Way Through

Canva on Mobile: Adopt It for Quick Visuals, Test It for Demanding Work

Google Drive Keeps Work Moving Until It Doesn’t

Switching to Weather - By Xiaomi Means Relearning Your Forecast Routine

Ludo King and the Social Life of a Lucky Six
When working through Ditch, I would compare the result of prioritizing the most expensive debt with the result of targeting a smaller balance first. The first approach can be financially efficient, while the second can provide a quicker sense of progress. The app is most useful when you use those options as decision aids rather than treating one result as an automatic command.
There is also a practical middle ground. You can keep minimum payments current across all accounts, direct a fixed extra amount toward one selected balance, and move that freed-up amount to the next balance after the first one is cleared. The important habit is consistency. Ditch works best when it supports a rule you can follow after a tiring week, not merely an ideal plan you admire once.
A realistic monthly scenario
Imagine that I have several revolving balances, a fixed amount available after rent and essentials, and a paycheck that arrives on a predictable schedule. I would use the app to record the balances, decide which account receives the extra payment, and check the plan before the next payment window. After paying, I would update the relevant balance rather than relying on memory.
That small update is easy to skip, but it is where the app becomes a habit instead of a one-time calculator. If I receive an unexpected refund or earn extra money, I can consider whether using part of it for the selected debt still leaves enough cash for necessities. Ditch helps frame that choice inside the broader payoff plan, while I remain responsible for the final decision.
For someone paid irregularly, the routine needs more care. I would avoid promising an extra payment until the income has arrived and the month’s essential bills are covered. A payoff forecast can encourage progress, but it should not tempt you to drain your emergency cushion or miss a required payment elsewhere.
The everyday workflow I would recommend
My preferred workflow is deliberately plain. First, gather current statements. Next, enter or review the debts. Then select a payoff priority and set an extra-payment amount that is genuinely affordable. Finally, check the plan whenever a balance, rate, minimum, or monthly budget changes.
I would also schedule a short review around an existing money habit, such as checking the account after payday. That is more reliable than opening a finance app only when anxiety appears. A repeatable check makes it easier to notice that a balance changed, a promotional rate ended, or an unexpected expense has altered what I can safely pay.
Settings and details worth checking
The most important “settings” in a debt app are often the details that shape its calculations. Before accepting a result, I would inspect the entered balance, interest information, minimum payment, and any due-date information the app uses. A plan can look precise while still being misleading if one of those details is stale.
I would pay special attention to whether an account has a temporary interest offer or a changing rate. A plan based on today’s conditions may not remain accurate after the lender changes the rate. In that situation, Ditch is still useful as a planning snapshot, but I would revisit it whenever the statement shows a meaningful change.
Another worthwhile check is the extra-payment amount. Setting it too high can create a plan that looks impressive but collapses when groceries, transport, or medical costs appear. I prefer a slightly conservative figure that survives ordinary months. If I later have more room, I can increase the payment rather than recovering from an overly ambitious commitment.
Because Ditch is a dedicated debt app rather than a complete household accounting system, I would keep a separate view of cash flow. The app can help organize the payoff side of the decision, but it should not be the only place where I assess upcoming bills, savings, and irregular expenses. That separation is a strength when you want focused debt planning, but it is a limitation if you expect one app to run your entire financial life.
Use small repeatable checks instead of constant monitoring
People sometimes assume that becoming serious about debt requires checking balances every day. I do not think that is necessary for most users. A better pattern is to update when something meaningful happens: a payment posts, a statement closes, a rate changes, or your available monthly amount moves.
That approach prevents two common problems. The first is stale information, where the app no longer reflects reality. The second is obsessive checking, where every small balance movement creates unnecessary stress. Ditch is most helpful when it provides a calm reference point for decisions rather than becoming another source of financial noise.
Faster patterns for experienced users
Once the basic plan is working, the next improvement is to remove repeated decisions. I would write down a simple rule such as, “minimums first, then all extra money goes to the selected target unless essentials are at risk.” Keeping that rule beside the app makes it easier to act consistently when an unexpected amount arrives.
A second useful pattern is to separate planned extra payments from occasional windfalls. The regular amount should be sustainable on ordinary income. A tax refund, gift, or side-job payment can be considered separately, after checking whether it is needed for a near-term obligation. This keeps the core Ditch plan realistic while still allowing faster progress during stronger months.
A third pattern is to update immediately after a target balance is cleared. Do not wait until the end of the month and then try to remember what happened. Refreshing the plan while the information is current makes the next target obvious and helps preserve the momentum created by the completed account.
I also like using the app as a conversation aid. If two people share expenses, the payoff plan can make a vague discussion more concrete: which balance is being prioritized, how much extra is comfortable, and what event would justify changing the amount. It does not solve disagreements about money, but it gives the conversation a common reference instead of relying on assumptions.
Where the app is faster than usual alternatives
A spreadsheet can be more flexible, especially for users who enjoy building formulas and tracking every transaction. It can also combine debt, savings, income, and bills in one custom model. The trade-off is maintenance. A spreadsheet often depends on remembering which cells to update and how the formulas work. Ditch’s narrower purpose is appealing when I want a debt-focused workflow without designing the system myself.
A bank’s built-in tools may show balances and transactions with less manual entry, but they usually reflect the institution’s own accounts or a broader financial picture. That is not always the same as a deliberate payoff strategy across several lenders. Ditch makes more sense when the question is not merely “what do I owe?” but “what should I pay extra next, and how do I keep following that plan?”
General budgeting apps can be better for controlling categories, spotting spending patterns, and planning a full household budget. I would choose one of those if my main problem were overspending or irregular cash flow. I would choose Ditch when the immediate challenge is organizing debt reduction and keeping the payoff priority visible.
Limits that deserve an honest look
The app cannot negotiate with lenders, erase interest, or guarantee that a projection matches the final statement. It depends on information being entered and maintained correctly. If you dislike manual updates or want automatic account synchronization as the center of your financial routine, a different type of finance product may suit you better.
It is also not a substitute for professional advice when debt is tied to legal action, collection activity, insolvency concerns, or a complicated tax situation. A payoff planner can help organize ordinary repayment, but serious financial distress may require a qualified counselor or adviser who can examine the full situation.
The optional purchase model is another point to consider. The app is free to install, but some items cost between $5.99 and $89.99 each. I would explore the free experience first and only pay for an option if I understood exactly how it improved my workflow. A paid feature is worthwhile when it saves repeated effort or gives information I will genuinely use; it is not worthwhile merely because debt feels urgent.
Privacy-minded users should also adopt a careful routine around financial information. I would enter only what the app needs for a useful plan, avoid treating it as a replacement for official statements, and keep the figures updated from trusted documents. That is sensible for any finance tool, especially one used to organize multiple obligations.
Who should use it, and who should skip it
Ditch is a strong fit for someone with several debts who wants a focused payoff plan, prefers a guided workflow to a self-built spreadsheet, and is willing to review information periodically. It is also useful for people who understand that motivation fades and want a visible routine that turns extra payments into a deliberate sequence.
I would be more cautious recommending it to someone whose primary need is expense tracking, bill reminders, investment management, or shared household accounting. Those users may find a broader personal-finance app more suitable. I would also skip it as a primary solution if my income were so unstable that even minimum payments were uncertain; in that case, cash-flow triage and professional guidance should come before optimizing payoff order.
My verdict after using the workflow
Ditch: Pay Off Debt Faster is best understood as a focused planning companion. Its value comes from helping me move from scattered balances to a selected priority, a realistic extra-payment rule, and a habit of updating the plan when circumstances change. That is more practical than a motivational slogan, but it still requires honest numbers and regular attention.
I appreciate that the app’s narrow focus can make debt feel less abstract. I also appreciate the trade-off: it does not replace a full budget, lender statements, or financial advice. The strongest results come from combining it with a simple cash-flow check and a repeatable payday routine.
With its Everyone age rating, free entry point, Android 8.0 support, and current version 1.5.6, it is accessible to a broad group of Android users. I would try it if my main question were how to organize repayment across multiple balances. I would not choose it simply because I wanted an all-in-one money manager.
My final recommendation is straightforward: use Ditch to make one payoff decision at a time, verify the information behind that decision, and keep the extra payment sustainable. The app is most effective when it becomes a quiet monthly habit rather than a dramatic one-day debt challenge. Used that way, it offers a focused and approachable path for people who are ready to take control of their repayment without pretending that an app can do the hard financial work for them.
Pros
- Clear payoff tracking helps users see progress toward becoming debt-free.
- Supports focused debt repayment strategies for better financial organization.
- Simple interface makes regular balance updates quick and convenient.
- Useful reminders can encourage consistent payments and financial check-ins.
- Helps turn a large debt balance into manageable repayment milestones.
Cons
- May require manual updates if your lender accounts are not supported.
- Limited value for users with complex loans or irregular repayment schedules.
- Debt payoff projections depend on accurate balances and interest information.
- Some useful planning features may be restricted to paid plans.
- Does not reduce debt itself; users still need sufficient income and discipline.
FAQs for Ditch: Pay Off Debt Faster
What is Ditch: Pay Off Debt Faster, and how does it work?
Ditch: Pay Off Debt Faster is a personal finance app designed to help you organize debts, understand repayment progress, and create a clearer plan for becoming debt-free. After entering details such as balances, interest rates, minimum payments, and due dates, the app can help you visualize what you owe and compare repayment approaches. It is primarily a planning and tracking tool, not a lender or debt-consolidation service.
Can Ditch help me choose the best debt repayment strategy?
The app is useful for comparing common repayment methods, such as focusing on the debt with the highest interest rate or paying the smallest balance first for quicker motivational wins. The most suitable approach depends on your balances, rates, income, and personal priorities. Ditch can make the numbers easier to understand, but its suggestions should be treated as educational guidance rather than personalized financial advice from a licensed professional.
Is Ditch: Pay Off Debt Faster free to download and use?
Ditch may be available to download at no initial cost, but some features can depend on the current subscription structure, in-app purchases, or regional availability. Before starting, review the app-store listing carefully for premium tools, trial periods, renewal terms, and cancellation instructions. Pricing and included features can change, so users should confirm the latest details directly in the Google Play Store or Apple App Store.
Is my financial information safe when using Ditch?
Because debt-planning apps may involve sensitive information, you should review Ditch’s privacy policy and permission requests before entering personal or account-related data. Avoid sharing banking passwords, card security codes, or other credentials unless the service clearly explains why they are required and how they are protected. Use a strong device passcode, keep the app updated, and check whether data is stored locally or synchronized online.
Does Ditch connect directly to my bank or make payments for me?
Ditch should be viewed mainly as a debt-management and repayment-planning companion unless the current version specifically states that it supports account connections or payment services. It does not automatically erase debt, negotiate with creditors, or guarantee faster repayment without additional money being applied to balances. Continue making required payments through your lenders, verify every due date independently, and contact creditors directly if you need hardship assistance or payment changes.

Ditch: Pay Off Debt Faster
This site provides independent information about third-party apps and is not affiliated with, or the owner, developer, or distributor of, any app featured here. App names, logos, and trademarks belong to their respective owners. Developer details are provided for reference; please contact the developer directly via hello@ditch.io, visit https://ditch.io, or review their https://ditch.io/privacypolicy.










